What accounting automation ROI looks like in year one
By Mara Voss · October 24, 2026
Category: enterprise-solutions
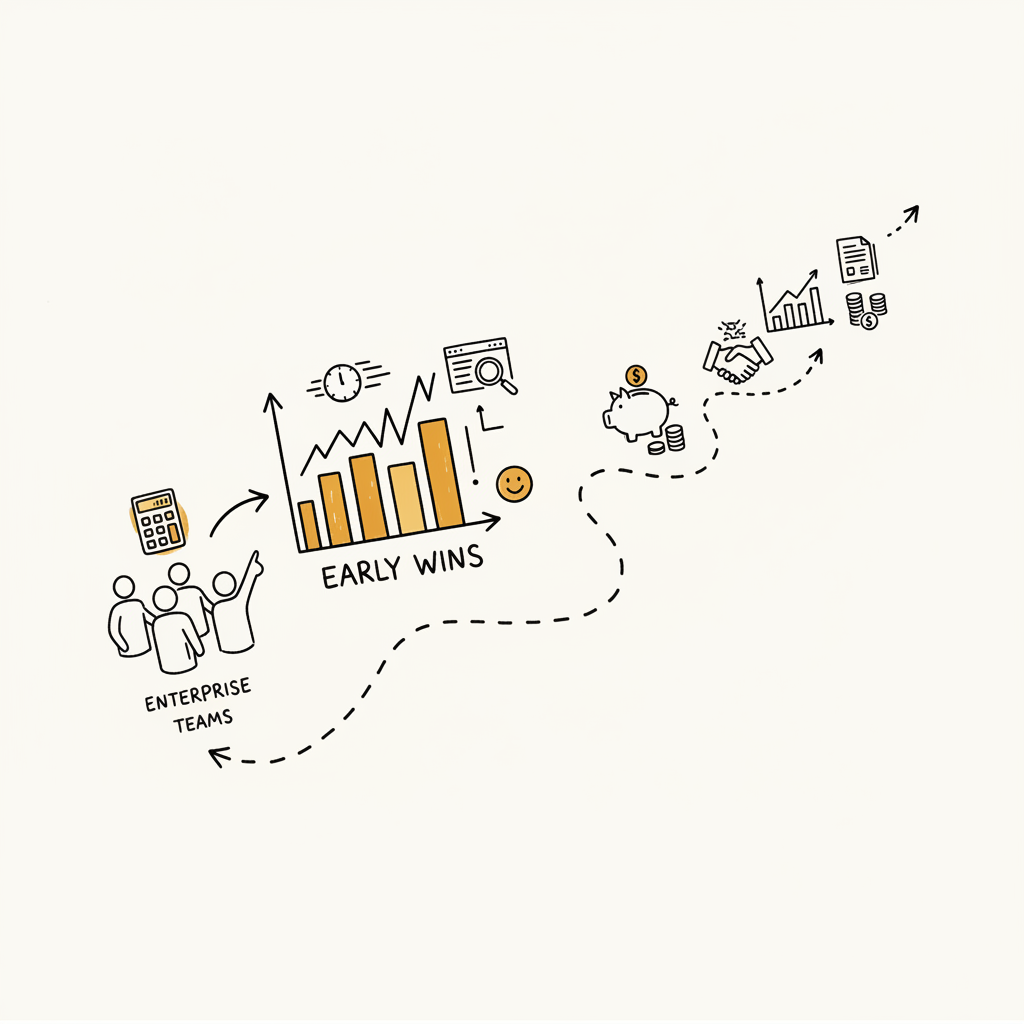
Automation ROI in accounting shows up in a different order than the business case predicts. Here is what enterprise teams see first, what comes later, and what to count.
Key takeaways
The problem Business cases promise hours saved in month one, then the first quarter delivers setup work and a dip in speed.
Core insight Returns arrive in a predictable order: control and visibility first, rework next, and capacity last, because capacity needs a decision about what people do with the time.
Practical outcome Baseline four numbers before you start and report them quarterly, including the cost of the review you still do.
The business case said the team would save thousands of hours. Three months in, the controller has a longer to-do list than before. Nobody lied. The case counted the savings and left out the work needed to collect them.
This article describes the order in which returns usually appear for enterprise accounting teams, and how to count them honestly.
Why the first quarter looks worse
New automation costs attention before it returns any. Someone must define tolerances, clean vendor records, write down rules that lived in one person's head, and review the system's first decisions line by line.
This is useful work. It is also the reason that you should not judge a project in week six. Judge it against a plan that expects a dip, and name the date when the dip should end.
The order in which returns appear
First: visibility and control
The earliest gain is often that you can see the process. Once exceptions are classified, you learn how many invoices lack a PO, which vendors send duplicates and which approvers hold items longest. You did not save time yet. You gained a map.
Controls improve at the same moment. A system that logs each decision with its evidence gives you a cleaner trail than an inbox of forwarded emails. That has value to your auditors even if it never appears as a cost line.
Second: less rework
Next, the loop of "post, find the error, reverse, repost" gets shorter. Errors caught before posting cost minutes. Errors caught in close cost a reconciliation and a conversation. Count reversals and correcting entries per month. The trend is a more honest measure than hours.
Third: capacity
Time frees up last, and only on paper at first. Two hours saved per person per week is not usable capacity until someone decides what to do with it. If nobody does, the hours dissolve into slack.
The firms gaining ground aren't working harder. They've changed what their teams work on. That requires a named plan: analysis of variances, vendor negotiations, earlier forecasts, or simply a close that ends sooner.
Four numbers to baseline before you start
- Touches per transaction. How many times does a person handle an item between arrival and posting?
- Exception age. How long does a flagged item wait before anyone acts?
- Rework rate. How many entries are corrected after posting?
- Close duration. How many working days from period end to sign-off?
Take these for three periods, not one, so a bad month does not set your baseline. Write the method down. If you later change how you count, you will not be able to compare.
The costs that case studies leave out
A fair ROI includes the full cost side. That means licenses and implementation, but also these items:
- Staff time for setup and the first review cycles.
- Ongoing review: someone samples the system's decisions every month, and that sampling has a cost.
- Vendor and master-data cleanup, which is often the largest hidden task.
- Change management: training, new procedures, and the period when two processes run side by side.
Review is not a flaw to eliminate. It is the control that lets you trust the rest. Budget for it and report it.
How to calculate it without fooling yourself
The basic form is simple: net benefit divided by cost, over a stated period. The general method is described in standard references on return on investment. The difficulty is not the formula. It is deciding what counts as benefit.
We suggest three rules:
- Count hours as benefit only where the hours were redeployed or a hire was avoided. Otherwise list them as capacity, separately.
- Count avoided losses, such as a duplicate payment stopped before release, only when you have the specific case.
- Show a range. A single number implies precision that nobody has.
What to expect at enterprise scale
Enterprise teams have more entities, more systems and more exceptions, so the setup is longer and the ceiling is higher. Differences in chart of accounts across entities, for example, mean that coding rules do not transfer. Plan each entity as a small project.
Published ROI figures from any vendor come from deployments that ran for a long time, not from a first month. Treat them as a ceiling, and treat your own baseline as the only number that matters for your case.
A reporting habit that helps
Report quarterly on the four numbers, the review cost, and a short note on what the team did with released time. Put the note first. The sentence "we moved two people to variance analysis" will persuade a CFO more than any percentage.
If the note is empty after two quarters, the project has a capacity problem, not a technology problem. Fix that before you extend the system.